EasyQuant · Quantitative Strategy Delivery

The quantitative investment lifecycle
in one system

Data · Research · Strategies · Backtesting · Risk · Execution · Accounting · Performance

The console, diagrams, screenshots and video currently use the Chinese interface. Blog articles and case studies are available in Chinese.

Built for quantitative funds, brokerage asset managers and institutional trading teams: each stage uses the actual results of the previous one. Backtesting, paper trading and live trading share the same logic, with explainable, reproducible and traceable results. Covers China A-shares, ETFs, futures, options and convertible bonds, with private deployment support.

Research production Versioning · Factors · Portfolio backtests · Optimization
Professional trading Options and spreads · Delta hedging · Grid strategies · Trading desk
Reliable governance Execution · Real-time risk · Reconciliation · Alerts and audits

WHAT WE ARE

The industry has alpha.
It needs a strategy delivery layer.

Research tools and trading terminals leave a delivery gap. EasyQuant turns individual research scripts into reproducible, diagnosable and governed assets that organizations can deliver.

Version governance Reproducible Diagnosable Unified accounting Risk audits Compliance records
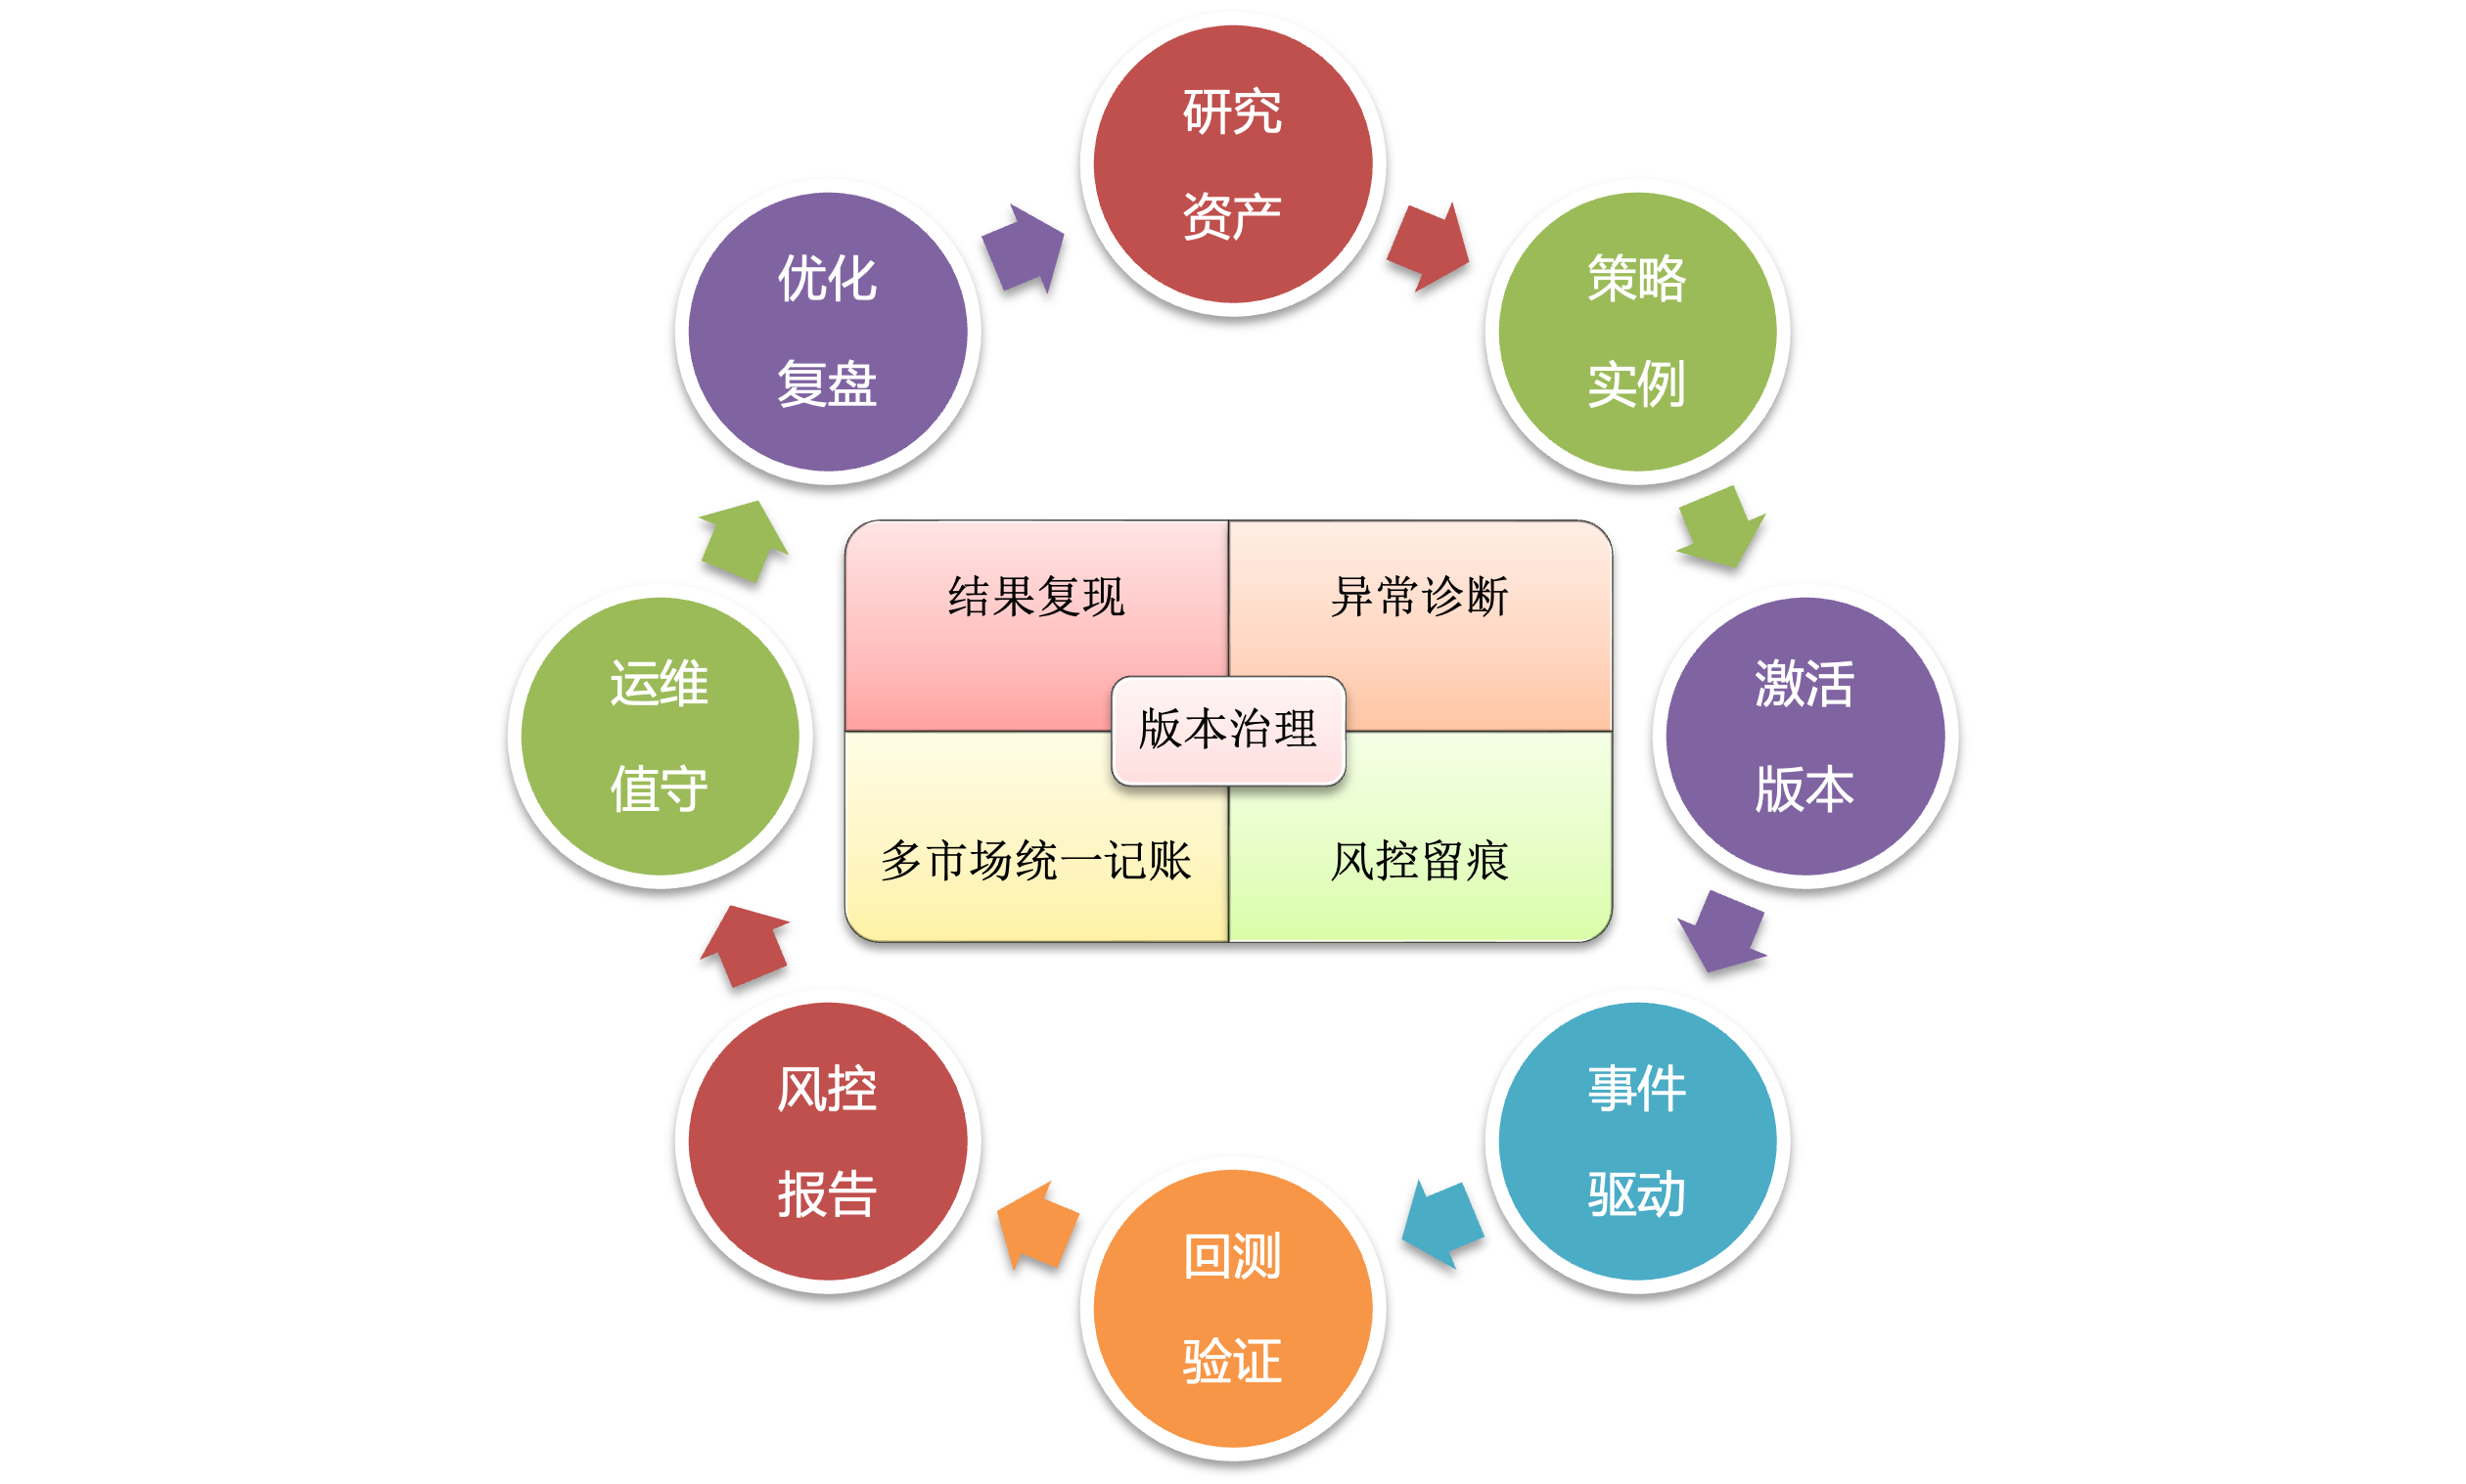
Strategy lifecycle: research assets, strategy instances, active versions, event-driven execution, backtest validation, risk reports, operations and optimization, centered on version governance
The strategy lifecycle centers on Version governance, with reproducible evidence at every step.
01 Challenge Irreproducible results Key-person risk

Strategies live in individual knowledge and laptops. Results differ across people and machines, and departures can disrupt continuity.

EasyQuant response Reproducible provenance

Automatic provenance snapshots help locate differences between backtests in 10 seconds.

02 Challenge Inconsistent definitions Accounting and ledger risk

Backtests, risk and live trading use different definitions; separate equity, futures and options ledgers make reconciliation and unified risk difficult.

EasyQuant response Unified accounting across five asset classes

Shared accounting across all three modes, with exchange-based options margin and consistent definitions and risk checks for A-shares, ETFs, futures, options and convertible bonds.

03 Challenge Missing records Compliance risk

Manual spreadsheets for submissions, cancellation rates and reviews cannot provide a coherent evidence chain for programmatic trading compliance.

EasyQuant response End-to-end records and audits

Gateway-level order-flow counters, live-order lineage and execution evidence support traceable audits.

04 Challenge Unexplained behavior Operational incident risk

Missing orders require guessing from logs; manual inspections find anomalies, and losses lack attribution.

EasyQuant response Diagnosable blocking reasons

Structured reason codes explain why an action did not occur, helping new operators narrow down issues in 10 minutes.

The bottleneck slowing quantitative teams is the missing delivery layer between research and live trading.

PLATFORM CAPABILITIES

Platform capabilities and modules

Each capability maps to business value, product modules and verifiable results across research, approval, execution, risk and ongoing operations.

Feature Map

The platform at a glance

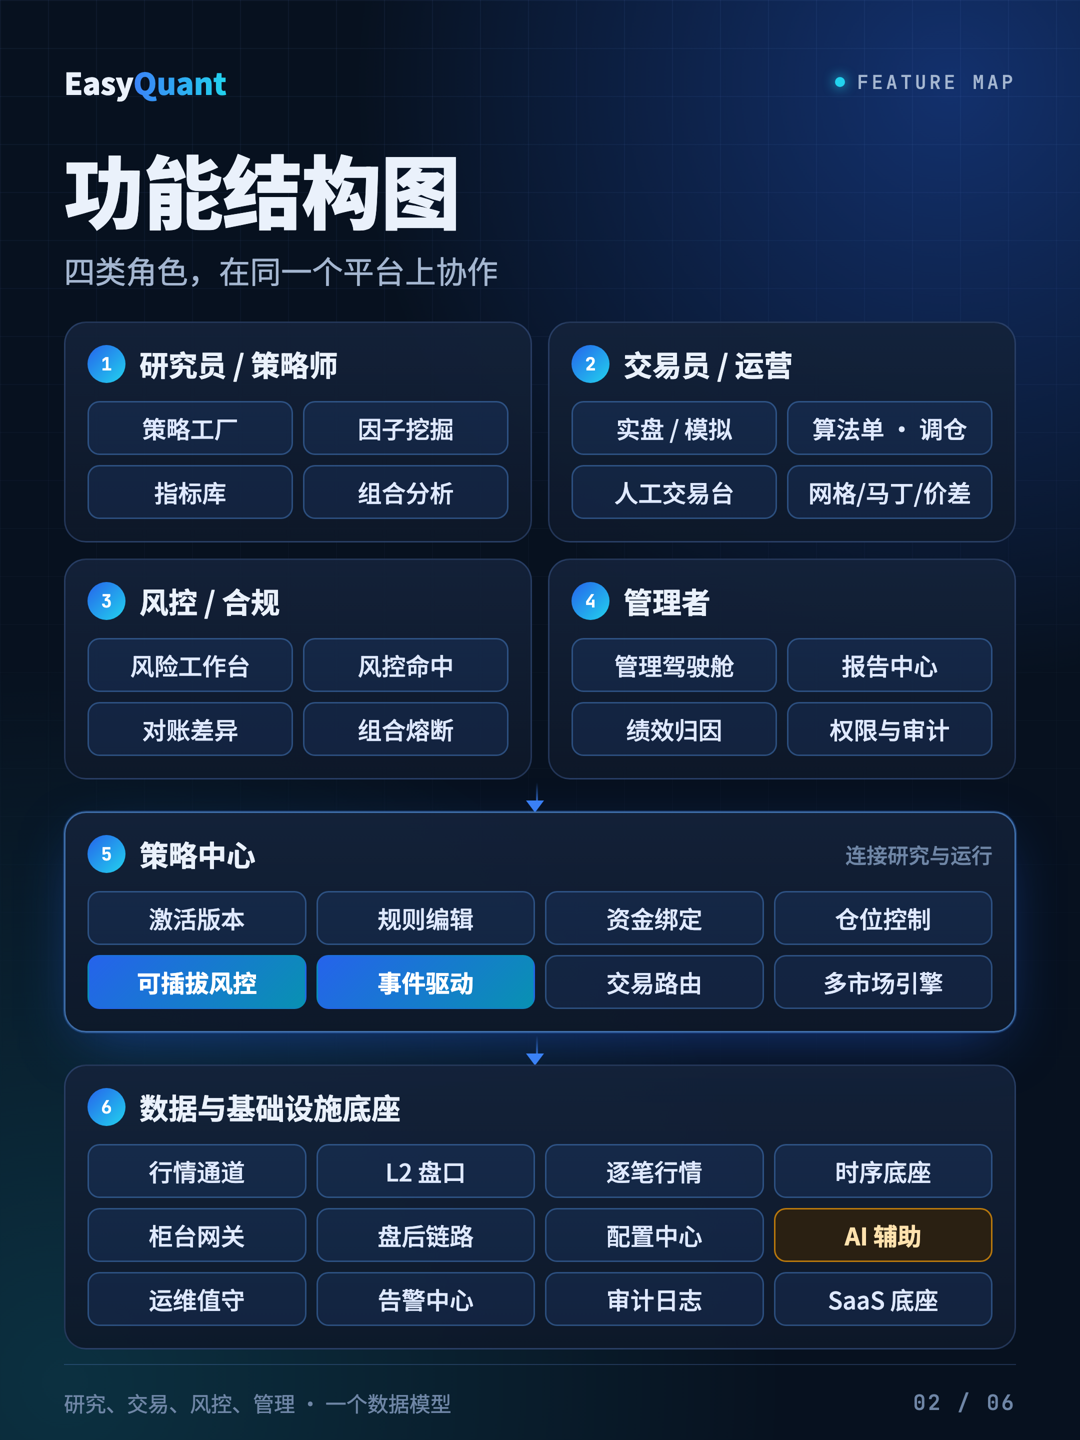
Four roles collaborate on one platform, sharing a strategy center and data foundation.

  • Researchers / Strategists: strategy factory, factor discovery, indicator library and portfolio analysis.
  • Traders / Operations: live and paper orders, algorithmic execution, rebalancing and manual trading.
  • Risk / Compliance: risk desk, rule hits, reconciliation differences and portfolio circuit breakers.
  • Managers: dashboards, reporting, attribution, permissions and audits.
Explore the full system
Researchers, traders, risk teams and managers share a strategy center linking research and operations, supported by a common data foundation

Research and strategy production

Turn research into reusable assets

The strategy factory connects projects, drafts, experiments, templates, releases and artifacts. Strategy versions, parameters, factors, universes and data ranges form runtime evidence.

  • Shared DSL and visual rules reduce divergence between research and runtime
  • Release gates, version comparisons, snapshots and rollback support collaboration
  • Signal replay and diagnostics explain triggers and missing fills
Strategy version → Parameter and factor snapshots → Backtest and runtime evidence
Backtesting, portfolios and investment decisions

Explain portfolio allocation beyond return curves

Backtesting, portfolio analysis and optimization cover returns, benchmarks, drawdown, costs, factor exposures, correlation, Brinson attribution, VaR and stress tests.

  • Portfolio backtests and TPE/grid optimization support pre-release evaluation
  • Barra styles and daily contribution breakdowns identify return sources
  • Backtest provenance links versions, data windows and cost models
Backtest validation → Portfolio attribution → Risk checks → Release decisions

Multi-asset and options capabilities

Consistent semantics across markets and risk factors

A-shares, ETFs, futures, options and L2 data, combining futures sessions, rolls and margin with options Greeks, volatility surfaces and portfolio risk.

  • Option chains, IV surfaces, portfolio Greeks and expiry risk
  • Delta hedging, spreads and multi-leg strategy analysis, execution and attribution
  • Central configuration for market behavior and data quality
Market data and contracts → Pricing and Greeks → Hedging and multi-leg trading

Strategy trading workbench

Bring professional strategies into one production workflow

Grid, martingale, turtle, ETF rotation and conditional orders reuse accounts, market data, risk and the order pipeline.

  • Structured management of parameters, sizing and execution methods
  • Clear boundaries between paper and live modes, with shared order and fill tracking
  • Research, production, operations and review share strategy assets and evidence
Strategy templates → Accounts and positions → Execution → Performance review

Algorithmic execution and trading desk

Make execution measurable

TWAP, VWAP, iceberg and sliced execution work with manual trading, conditional orders, order-flow controls and quality tracking. A common adapter layer connects broker channels.

  • Track parent orders, child orders, fills and remaining quantities
  • Slippage, rejections, fill rates and execution reasons form quality evidence
  • Channel availability and account connection states are shown separately for environment-specific acceptance
Strategy intent → Algorithmic parent order → Child orders and fills → Execution attribution

Real-time risk and operations governance

Risk controls with actionable, auditable outcomes

Pre-release checks, account and portfolio limits, drawdown breakers, futures margin and options Greeks share one workbench, with consistent risk messages, rejections and reconciliation.

  • Overview, reconciliation, rule hits, alerts and resolution form an operations loop
  • Locate risk by account, strategy, market and rule
  • Reports, audits, job records and metrics support ongoing operations
Pre-trade gates → Runtime checks → Reconciliation → Reports and audits

AI enhances product help, risk and execution diagnostics, backtest summaries and factor-formula assistance.

CASE STUDIES

Strategy governance case studies

Public strategies are backtested, simulated and attributed in EasyQuant to demonstrate reproducibility and auditability. Published rules allow independent comparison and review.

01 Reproducible

Dual-low convertible bond rotation

Can the same public strategy produce verifiable results across people and machines? Three input hashes help locate result differences in 10 seconds, while versioning turns individual work into a team asset.

Read the case study (Chinese)
02 Attributable

Dividend low-volatility and multi-factor screening

Where do excess equity returns come from: style, luck or skill? Brinson and Barra attribution break down the sources of returns, with one NAV source for investor, compliance and audit reporting.

Read the case study (Chinese)
03 Auditable

Grid and spread arbitrage

Frequent-order strategies need visible exposure controls. Each order passes explainable pre-trade checks; rejections carry a reason, with both legs viewed together and account circuit breakers controlling risk.

Read the case study (Chinese)

BY THE NUMBERS

One system, this much coverage

Each item maps to a module already running in the console — enable what you need without changing the core.

7 asset markets A-shares, ETFs, futures, options, convertible bonds, US equities and crypto
8 broker gateways integrated CTP, QMT, XTP, TORA, PTrade, IBKR and more, in paper and live modes
9 market data sources Automatic primary/backup failover, and your existing commercial feeds can be connected
16 pluggable risk rules One pre-trade check that no source can bypass
3 backtest engines Equity portfolios, derivatives portfolios and single instruments, on the same definitions as live trading
4 execution algorithms TWAP, VWAP, POV and iceberg, with execution quality measured order by order
200+ strategy indicators An open AlphaSpec indicator catalog, each with parameter notes and common pitfalls
20 MCP tools Agents can call backtests, evaluation and execution evidence — never order placement

The full list of broker gateways, data sources and technology stack is on Ecosystem; AI research and the open contract are on AlphaSpec

USE CASES

Quantitative workflows for different organizations

Adapt one foundation to different teams through tenants, permissions, workflows and modules. Select capabilities according to business goals.

Quantitative funds

Standardize the path from research to trading

For quantitative funds building strategy assets, controlling release quality and managing account risk and execution quality.

Strategy factory Portfolio backtests Release gates Real-time risk
Typical outcome: A complete evidence chain across research versions, production instances, fills and risk resolution.
Asset managers

Manage products, accounts and portfolio risk together

For brokerage asset managers, managed accounts and teams measuring exposure, performance and risk by product and account.

Product NAV Barra attribution Brinson VaR and stress tests
Typical outcome: Consistent reporting of strategy contributions, allocation, exposure and product NAV.
Institutional trading and research teams

Support multi-asset research and professional trading

For teams researching equities, ETFs, futures and options and validating ideas through algorithmic orders, hedges and multi-leg strategies.

Options and Greeks Delta hedging Multi-leg spreads Algorithmic execution
Typical outcome: Link research hypotheses, portfolio risk, trade intents and final fills.
University teaching and research

A practical, verifiable teaching environment

For financial engineering, computing and data science courses demonstrating factors, strategies, backtesting, paper trading and risk with real market semantics and isolated class, project and experiment data.

Course tenants Strategy DSL Historical backtesting Market data and signal replay
Typical outcome: Students submit reproducible experiments with versions, data ranges and backtest results.
PaaS and white-label integration

Build your quantitative product on a shared core

For brokerages, fintech providers and partners reusing strategy, backtest, risk, execution and tenant capabilities with their own branding, permissions, modules and channels.

Multi-tenancy and RBAC Modular capabilities API integration Branding and workflow configuration
Typical outcome: Reduce the effort of building trading infrastructure and focus on customer workflows and differentiated products.

CONTROL TOWER

Management and observability

Monitor five operational questions: system health, risk location, execution effectiveness, research quality and issue resolution.

BUILT ON EASYQUANT

Products built on the platform

Products reuse the same strategy, data, backtesting and runtime foundation and evolve with the platform.

FIRST PRODUCT

EasyQuant · Personal Edition

The personal edition is the first product built on EasyQuant. It organizes strategy expression, historical validation, paper trading and performance review into a clear workflow, demonstrating how platform capabilities can support specific products.

Readable strategy rules Historical validation Paper trading tracking Performance and risk review
Explore the personal edition

FAQ

FAQ

Questions about evaluation and implementation.

How does the website differ from the console?

This website presents capabilities and architecture. The console contains the actual features and environment. Contact sales to try it; integration scope is agreed during delivery.

What is a quantitative strategy delivery platform?

EasyQuant is a Quantitative strategy delivery platform: strategies become deliverable, diagnosable, governed and reproducible organizational assets. One workflow connects the strategy factory, versions, backtests, event-driven paper and live trading, risk, reconciliation and reports.

What capabilities does the integrated research and trading platform provide?

Multi-asset research, strategy production, three backtest engines, algorithmic execution, options and multi-leg trading, real-time risk, reconciliation and operational audits, connected by one evidence chain.

Which markets and broker gateways are supported?

Unified equity, futures and options management with CTP, OPENCTP, QMT, XTP, TORA, EMT, PTRADE and IBKR gateways, supporting PAPER and LIVE execution modes.

How long does implementation take?

Timing depends on tenant scale and data scope. A standard pilot first establishes the core workflow; schedules are confirmed after commercial and technical assessment.

How is strategy release quality controlled?

Pre-release checks validate DSL, parameters, risk configuration, experiment gates and bindings. Failed checks prevent activation, with review and audit records throughout.

Book an EasyQuant demo

Discuss an implementation plan and business case based on your team, strategies and risk requirements.

WeChat enquiries EasyQuant WeChat contact QR code Scan to add us on WeChat for demos and business enquiries Email our sales team Try the console